How to navigate election uncertainty, potential tax increases, and Social Security risks without overreacting to Washington.
- Social Security’s retirement trust fund is projected to run short in 2032, but Washington policy expert Jeff Bush doesn’t expect Congress to let a 22% cut happen.
- At Gryphon Wealth’s October 13 event on the midterms, Jeff expects Democrats to win the House and called the Senate a coin toss.
- With Washington’s direction uncertain, the rules already on the books are the ones to plan around.
Twenty-two percent. That’s how much every Social Security retirement check could shrink in late 2032 if Congress does nothing.¹ Jeff Bush, principal of The Washington Update, a non-partisan financial and political analysis group, doesn’t think Congress will let that cut happen. I’ve sat through a lot of Social Security talks, but until he brought it up recently, I’d never heard it put quite that way.
Here’s what Jeff told us about midterms, Social Security, tariffs and taxes, and what we think it means for your plan.
Jeff Bush’s Midterm Forecast: A Democratic House and a Senate Toss-Up
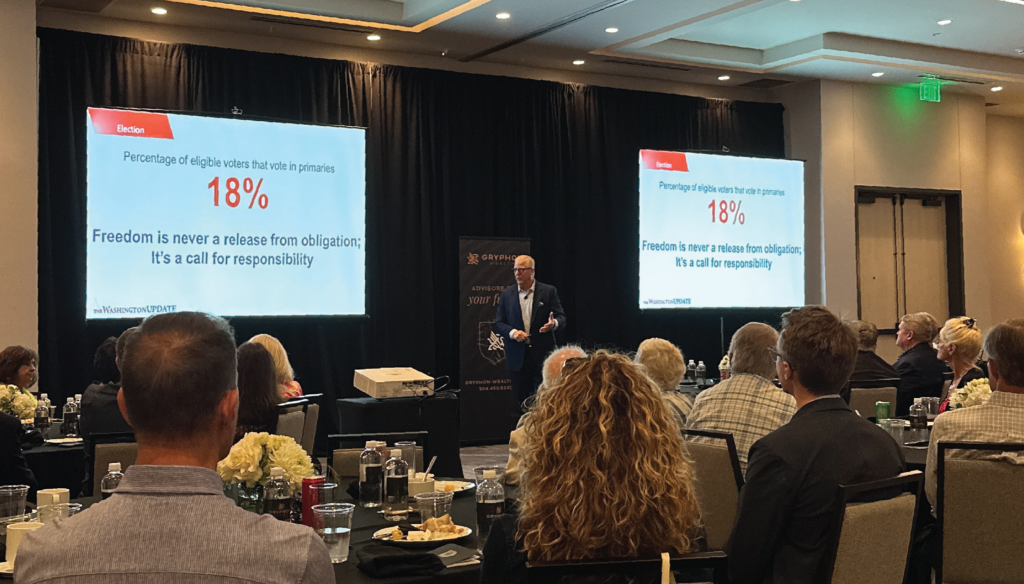
On October 13, Gryphon Wealth clients joined us at the Hilton Jacksonville for breakfast and lunch sessions with Jeff Bush, Jeff expects Democrats to win the House and calls the Senate a coin toss. He sees the election as a referendum on the economy as households feel it: higher prices for groceries, school supplies, and holiday gifts, to name a few.
- House: In his base case, Democrats win a majority of roughly 10 to 15 seats
- Senate: He leans toward a narrow Republican hold but gives Democrats a real chance. The result may not be known until December or January.
He points out that most states are more competitive than the red-and-blue maps suggest. Even Florida has split about 51.5% Republican to 48.5% Democratic across presidential races from 2000 to 2024.² That matters in House races, where every seat is local.
What Would Divided Government Mean?
When a client calls me worried about the election, I bring in a lot of what Jeff had to say: we are likely headed for divided government (one party in the White House, the other controlling at least one chamber of Congress). If Republicans lose the House, expect them to push priorities through budget reconciliation (a fast-track budget process that needs only a simple majority in the Senate) and a year-end spending bill, possibly including the debt ceiling (the legal cap on how much the government can borrow). After that, anticipate gridlock, more executive orders, and louder rhetoric. Rhetoric isn’t legislation. Plan accordingly.
What Happens to Social Security Benefits in 2032?
Of everything Jeff covered, I think our clients will most feel his points about Social Security. The trustees project that the program’s retirement trust fund can pay full benefits until late 2032. After that, incoming payroll taxes would cover about 78% of scheduled benefits, a 22% cut for everyone, unless Congress acts.¹
Jeff doesn’t expect that cut to happen. He believes Washington acts when ignoring a problem hurts more than fixing it, and that people already collecting, or within about 10 years of full retirement age, are likely to be largely spared.
I can think of a few couples we work with who are in their mid-70s with about $80,000 a year in Social Security and a $20 million portfolio. A 22% cut would mean about $17,600 less a year. That might not sound like the kind of money that would change how they live, but people tend to react emotionally when it comes to money. They remember when $17,600 was a good salary and they paid in for decades. A cut just feels wrong.
Much of our work is helping families make sound decisions when money stirs up feelings. So we don’t start by telling anyone not to worry. We start by running the numbers.
Jeff assumes Social Security benefits will grow just 1.5% a year, less than inflation is expected to run. There’s a reason to consider that possibility. Annual increases, called cost-of-living adjustments (COLAs), are tied to an index that tracks prices for working households, while a separate index measuring older Americans’ expenses has historically risen somewhat faster. Lawmakers have even proposed using a slower-growing measure, which would reduce annual increases by about a quarter of a percentage point.
We’re testing Jeff’s plan against those assumptions, including a 22% benefit cut in 2032. The question is whether those assumptions would change what a client can comfortably spend or give away today. In our experience, it often doesn’t, and when a client sees that in their own numbers, it’s more convincing than words of reassurance.
The Real Cost of Tariffs: Investment That Isn’t Happening
Jeff expects tariffs to stay, even after the Supreme Court struck down the administration’s emergency-powers tariffs on February 20, 2026. The bigger cost may be the investment that isn’t happening.
When it comes to tariffs, my biggest concern isn’t the grocery bill. Businesses don’t want to invest money when they don’t know the rules of the road. Would a CEO build a plant if the next administration might reverse the tariff that makes it pay off? Jeff made a similar point in the Q&A: companies are retooling existing facilities more than building new ones. That hesitation is a drag on an economy that could otherwise be on firmer footing, and business owners planning a sale may want to factor it into their timeline.
Why Do Historically Low Tax Rates Matter Now?
The central planning message from the sessions was that today’s tax rates are historically low, and that families should diversify their tax exposure (avoid having all your wealth taxed the same way) so future law doesn’t make their decisions for them. One slide had an idea I found especially well said: “You can’t tax enough. You can’t cut enough. You can’t grow enough.” Jeff’s point: putting the country on stable footing will take not only more revenue but also spending cuts. That tells me which way the long-term pressure on taxes points, and why the rules we know today are worth using now.
Jeff expects estate taxes to rise eventually; I suspect income taxes are the likelier target. Either way, the lesson is the same. Under current law, the estate and gift exemption is $15 million per person, and December 31 is the last day for 2026 annual gifts.³
Charitable Giving: Why Bundling Gifts Can Help
Charitable giving deserves a closer look this year. With the new 0.5% of income floor on charitable deductions, bundling several years of gifts into one can help.4 Many families bundle through a donor-advised fund (a charitable account that lets you take the deduction now and recommend grants to charities over time), while still giving to their church or school every year.
Clients age 70½ or older can also give directly from an IRA to charity, called a qualified charitable distribution (QCD).
Planning a Business Sale?
Business owners may want to ask whether the expanded qualified small business stock (QSBS) rules under Section 1202 could apply to a future sale.
Our View: Plan Around the Rules Already on the Books
We’re likely heading into a busy December and then two years of gridlock. In our view, neither is a reason, on its own, to revamp investments. Both are reasons to act on what’s already in law. The tax code in front of us is the one we know, and December 31 is the next real deadline on the calendar.
Thank you to everyone who joined us, and to Jeff for two lively sessions. If you’d like to run a Social Security scenario, review year-end gifts, or talk through charitable bundling before December 31, reach out to your Gryphon Wealth advisor. Not a client yet? We’d welcome the conversation.
Sources
- The 2026 OASDI Trustees Report (Social Security Administration)
- Jeff Bush, The Washington Update, “America’s Political Landscape: 2000–2024,” presented October 13, 2026, based on MIT Election Data and Science Lab presidential election returns
- Revenue Procedure 2025-32 (Internal Revenue Service)
- The Charitable Giving Efficient Frontier in the OBBBA Era (Financial Planning Association)
Disclosures
Gryphon Wealth, LLC is an investment adviser registered under the Investment Advisers Act of 1940. Registration as an investment adviser does not imply any level of skill or training. For more information, please visit adviserinfo.sec.gov and search for our firm name.
This article was created with the assistance of artificial intelligence as part of our research and drafting process. Every piece of content is reviewed, edited and approved the Gryphon Wealth team before publication to ensure accuracy, clarity and alignment with our values. The final perspective shared here is our own.
This material is presented solely for informational purposes and has been gathered from sources believed to be reliable; however, the adviser cannot guarantee the accuracy or completeness of such information. Nothing in this presentation is intended to serve as personalized investment, tax, or insurance advice. Advisory services are only offered to clients or prospective clients where the adviser and its representatives are properly licensed or exempt from licensure.
Opinions expressed are based on economic or market conditions at the time this material was written. Economies and markets fluctuate. Actual economic or market events may turn out differently than anticipated. Any opinions expressed are current only as of the time made and are subject to change without notice.
The article discusses tax outcomes related to the sale of a business. It is not tax advice. Please consult your tax advisor regarding your specific situation.
Client examples described in this article are included for illustration. They are not testimonials, do not describe investment performance and should not be taken as representative of any other client’s experience.
Past performance is not indicative of future results.