- OBBBA (the One Big Beautiful Bill Act, signed into law in 2025) adds a new ~$1,000 (~$2,000 for joint filers) charitable deduction for non-itemizers, and reduces the deduction for top-bracket donors on large gifts.
- Donor-advised funds remain an effective tool to simplify record-keeping, gift appreciated stock, and control the timing of a deduction.
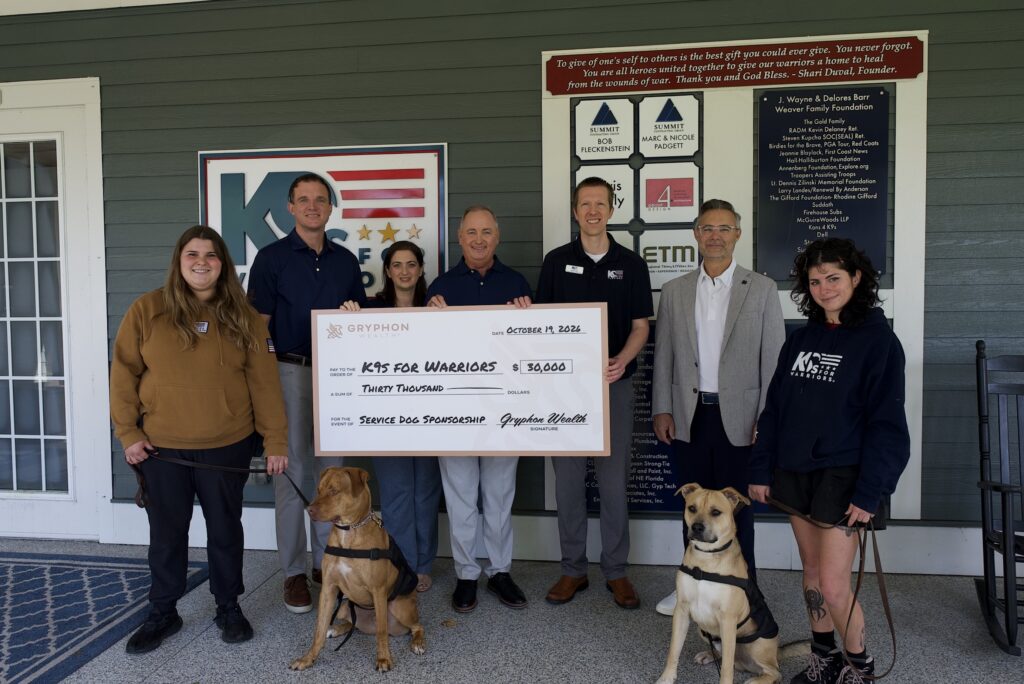
- Gryphon Wealth’s own Giving Fund made its first gift in 2026: $30,000 to K9s For Warriors to train a service dog for a veteran who may have post-traumatic stress disorder (PTSD), traumatic brain injury or military sexual trauma.
My co-founder, Jeff Wyatt, has a short list of topics he says clients raise with him again and again. Charitable giving sits at the top. Not “how do I get a bigger deduction” — something more human. Our clients have spent decades building businesses, relationships, and lives, and most of them are very charitable. What they want to know is whether they can give without putting their own security, or their family’s, at risk.
In our practice, we spend nearly as much time on charitable planning as we do on Roth IRA conversions, and for a firm built around retirement income and multigenerational wealth, that means charitable giving comes up a lot.
Here’s what OBBBA actually changed for charitable giving, and why the fundamentals of giving effectively still matter more than any single tax rule.
Question One Is Never About Taxes
Before anyone talks about deductions, we start with a more basic question: can the client afford to make this gift without changing their lifestyle? We recently spent six months working with a family whose wealth spans generations, walking through the details of a large gift to a hospital they’ve supported for three generations. They’re the kind of family whose generosity outpaces even their own planning, generous enough that our job becomes less about finding room for the gift and more about protecting their needs and lifestyle while making as much of it tax-deductible as possible. The dollar figure was significant, and every conversation started with the same instinct: protect the family’s security first and let the generosity follow from that basis.
Similarly, someone we work with has a portfolio of a few million dollars, and had been giving five or ten thousand dollars a year, assuming that was their limit. Once we ran the numbers, it became clear they could comfortably give an order of magnitude over their original amount every year without touching their own retirement security.
Confidence matters in the other direction too. Sometimes we must talk clients out of gifts they want to make solely for the tax benefits. If a client is in a high bracket and gives away a dollar expecting to get most of it back through a deduction, the math rarely works the way they anticipate. They’re still meaningfully out of pocket. If the charitable motivation isn’t there, the tax savings alone shouldn’t be the deciding factor.
What OBBBA Changed for Charitable Giving in 2026
Once the “can I and should I” questions are answered, there are three One Big Beautiful Bill Act (OBBBA) changes worth considering.
- There’s a new, modest deduction. It’s up to $1,000 for single filers and $2,000 for joint filers, and it’s available even for taxpayers who take the standard deduction rather than itemizing.1 It’s a small number, but it means charitably inclined households who don’t itemize now have something to show for their giving on their tax return.
- Starting in 2026, charitable gifts only count toward a deduction once they exceed 0.5% of adjusted gross income for the year.2 For most of our clients, whose giving already runs well above that threshold, this doesn’t change much. But it matters for the timing conversation — a household weighing whether to make one larger gift this year versus several smaller ones over multiple years now has an added reason to bunch giving, since spreading gifts too thin across years risks losing part of the deduction to the floor each time.
- Taxpayers in the top tax bracket can no longer count on a full dollar-for-dollar deduction at their top rate.3 The new rules essentially trim a couple of percentage points from the benefit of a large gift made in the top bracket. It’s a real change, but it doesn’t usually impact what a charitable client does. It mostly changes how much of the gift’s cost the government is picking up.
Why a Donor-Advised Fund (DAF) Still Makes Sense
There are practical strategies to keep in mind. For most of our clients, a donor-advised fund (DAF) is the cleanest tool available, for three reasons.
Simpler Record-Keeping
One is simplicity. Instead of tracking dozens of individual gift receipts for an accountant, a DAF gives the donor a single record for the money that goes in, and it can be distributed to as many charities as desired afterward without tracking any of those individual distributions. Some clients use the fund just for that record-keeping benefit, moving money in and out the same year.
Giving Appreciated Stock
The second reason is appreciated stock. Gifting long-term appreciated shares directly into a DAF, rather than cash, avoids capital gains tax entirely — for the donor and for the charity. A client who donates, for instance, a highly appreciated position with a large embedded gain gets the full fair-market-value deduction, and neither side ever pays tax on the built-in gain. This only works with long-term holdings; stock held a year or less, or a position sitting at a loss, doesn’t get the same treatment, since the deduction is capped at cost basis rather than fair market value, so we steer clients toward selling short-term gains and losses themselves rather than donating them outright. Because there’s no wash-sale rule (the IRS restriction that normally blocks you from immediately buying back an investment you sold at a loss) on a charitable gift, it’s also possible to gift the appreciated shares and then buy back the same position with cash that was otherwise earmarked for the gift. From then on, the position carries a higher cost basis. We use this regularly for clients who want to keep giving cash-equivalent amounts while cleaning up a portfolio’s embedded gains.
Controlling the Timing of the Deduction
The third advantage of donor-advised funds (DAF), and this is a huge one, is timing. Large gifts are often too big to allow a household to fully deduct in a single year. A DAF lets a donor separate the timing of the deduction from the timing of the money reaching the charity. A lump-sum contribution can go into the fund now, with the deduction taken this year. We often time that lump sum to a client’s highest-income year – a final year of employment, the sale of a business, a large bonus or a vesting event – bunching several years’ worth of giving into the fund at once to capture the deduction when it’s worth the most. The fund can then distribute consistently to the causes supported over several years without messing up their cash flow.
Gryphon Wealth’s DAF Platform and Giving Fund
We built our DAF platform, in partnership with UI Charitable, to reflect that same philosophy: keep the fee structure simple and low. It’s a quarter of one percent for accounts we manage – on top of University Impact’s own modest platform fee for administering the account, which applies either way – nothing for clients who simply want the record-keeping benefit. The tool is flexible enough to serve a five-thousand-dollar annual giver and a ten-million-dollar capital campaign the same way.
We back that philosophy with our own giving. In 2026, we launched the Gryphon Wealth Giving Fund, the firm’s own charitable vehicle, focused on military members, Veterans and first responders. It’s a good fit for a firm headquartered in a military town like Jacksonville, Florida, and a cause close to Jeff’s heart, given his Navy background. The fund’s first gift was a $30,000 contribution to K9s For Warriors, covering the full cost to train a service dog and pair it with a veteran managing PTSD. It’s an example of the same principle we bring to every client conversation: give generously and thoughtfully, but also structure giving sustainably.
Bottom Line: What to do Before Year-End
For clients and others committed to charitable giving, now is the time to talk with an advisor about timing. Does it make sense to do a larger gift this year or to spread it across several years? Also consider whether appreciated stock makes more sense than cash, and whether a donor-advised fund would simplify things. Some details around charitable rules have changed over the past year. What remains the same is the goal: give generously, without risking the security a family has spent a lifetime building.
Anyone weighing a year-end charitable gift — whether already a Gryphon Wealth client or simply exploring options — is welcome to reach out and talk through the timing and structure that make the most sense for their situation.
Frequently Asked Questions
- Do I need to itemize to get a charitable deduction under OBBBA?
No. OBBBA added a new deduction of up to $1,000 (single filers) or $2,000 (joint filers) for taxpayers who take the standard deduction instead of itemizing. - What is a donor-advised fund (DAF)?
A DAF is an account you contribute to now, taking the tax deduction in that year, and then recommend grants over time to the charities you choose, on your own schedule. - When does the new charitable deduction floor take effect?
Starting in 2026, itemizers can only deduct charitable gifts once they exceed 0.5% of their adjusted gross income for the year.
Sources
- Beth Shapiro Kaufman et al., “OBBBA Provisions Impact Charitable Contribution Deductions,” Lowenstein Sandler LLP, July 16, 2025.
- Ibid., “Creation of a Floor for Charitable Deductions for Itemizers.”
- Ibid., “Maximum Benefit From Charitable Deduction Limited to 35 Percent Tax Rate.”
Disclosures
Gryphon Wealth, LLC is an investment adviser registered under the Investment Advisers Act of 1940. Registration as an investment adviser does not imply any level of skill or training. For more information, please visit adviserinfo.sec.gov and search for our firm name.
This material is presented solely for informational purposes and has been gathered from sources believed to be reliable; however, the adviser cannot guarantee the accuracy or completeness of such information. Nothing in this article is intended to serve as personalized investment, tax, or insurance advice. Advisory services are only offered to clients or prospective clients where the adviser and its representatives are properly licensed or exempt from licensure.
This material discusses potential tax implications of charitable giving. This is not tax advice. Please consult your tax advisor regarding your specific situation.
Opinions expressed are based on economic or market conditions at the time this material was written. Economies and markets fluctuate. Actual economic or market events may turn out differently than anticipated. Any opinions expressed are current only as of the time made and are subject to change without notice.
Investing involves risk, including the possible loss of principal. Past performance is not indicative of future results. This article was created with the assistance of artificial intelligence as part of the research and drafting process.